The SEC canceled its August 14 vote on Regulation Crypto one day before the meeting. The Office of the Secretary posted a Sunshine Act cancellation notice on August 13, CryptoDaily reported, citing an unforeseen scheduling issue. No substantive explanation followed, and no new date has been set.
Our earlier piece said Friday's vote was expected to pass without drama. The SEC's three commissioners were due to meet at 10 a.m. ET, with Regulation Crypto as the only agenda item. The proposal is a 400 page package that had cleared the White House regulatory review office and needed only three friendly votes to enter its comment period. Instead the item was pulled.
Sunshine Act notice, scheduling issue cited.
Reg Crypto unscheduled, not withdrawn.
Industry executives convene on digital assets.
Crypto's Regulatory Evolution session.
A scheduling issue with no new date
Sunshine Act cancellations happen, but agencies that intend to proceed usually reschedule in the same notice, and this one did not. Six Division of Corporation Finance staff members were slated to present. The commissioners were publicly aligned, and reporting all week had treated publication as a formality. Then the item disappeared from the calendar with a single procedural line.
Until a fresh notice appears on the SEC's open meetings page, no vote is pending on the first crypto-native offering regime in the agency's history. Nothing in the notice withdraws the proposal. Its three pathways sit where they sat in March: drafted, reviewed and unproposed. They are a $5 million startup exemption, a $75 million fundraising exemption and a decentralization safe harbor.
The clock is the part we keep returning to. Commissioner Hester Peirce, the proposal's intellectual godmother, departs in November. A commission of two is a hard place to launch ambitious rulemaking, which is why the August date existed. Every week the vote stays unscheduled spends down the margin, and an agency that wanted the rule out could have picked any day next week. In our reading, that turns a scheduling footnote into a signal.
The other agency's busy week
The timing is pointed because of what surrounds it. Tech Times framed the contrast directly: as the SEC stepped back, the CFTC stepped up. On August 19 the White House convenes a digital asset roundtable with industry executives, and Polymarket's Shayne Coplan is among the confirmed names, TFTC reported.
One day later the CFTC holds the inaugural session of its Innovation Advisory Committee, from 1 p.m. to 4 p.m. ET in Washington. The session is titled Crypto's Regulatory Evolution: From Uncertainty to Clarity, with digital assets, autonomous AI agents and prediction markets on the agenda.
An advisory committee produces recommendations, not rules, so the concrete output will be modest. The sequence is another matter. An executive branch summit, a commodities regulator advertising its crypto ambitions and a securities regulator going quiet in the same five day window are being read across the industry as a deliberate rebalancing of who writes the rules.
Our earlier piece flagged that a rule adopted by one commission can be unwound by the next. A rule that is never proposed needs no unwinding at all.
A market already leaning the wrong way
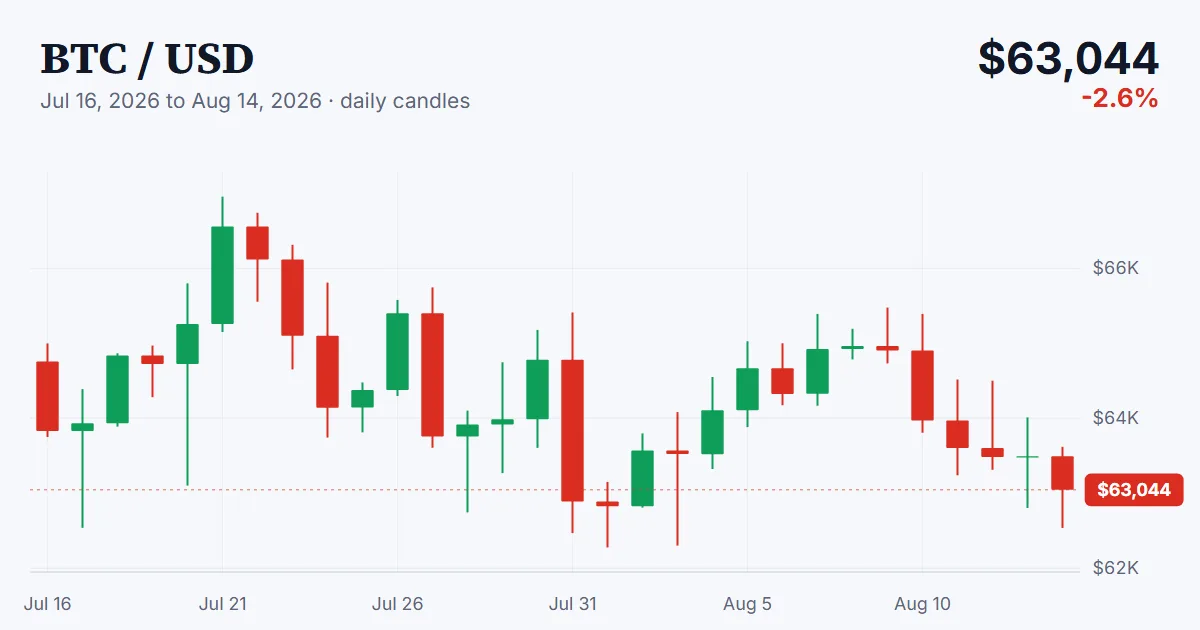
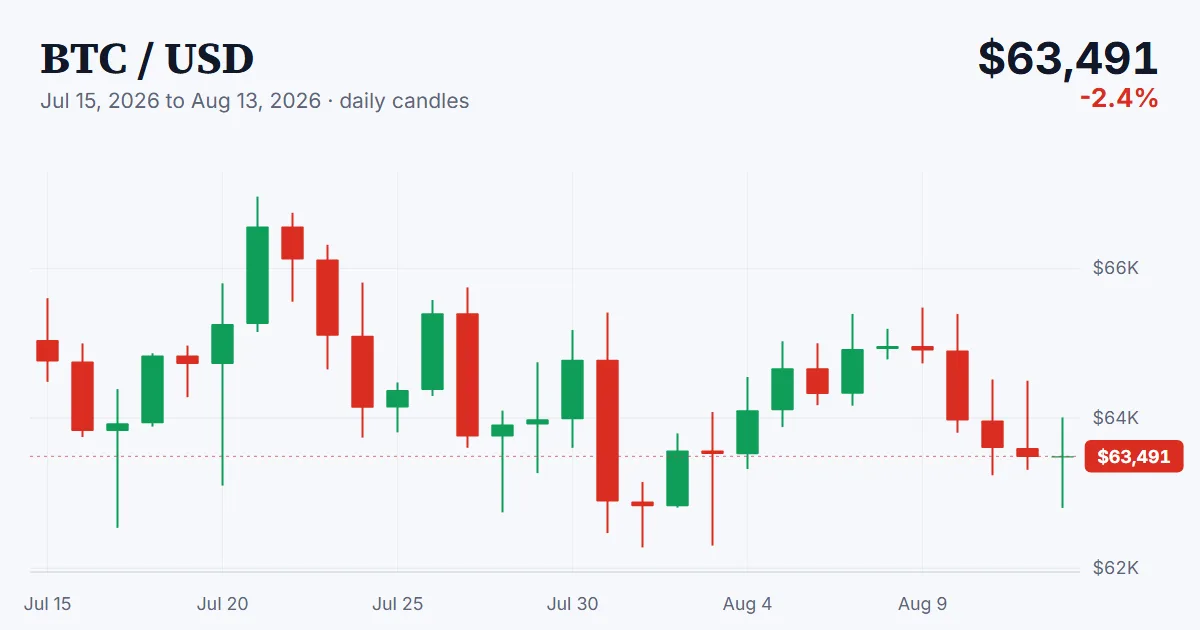
The market took the news without a sharp move, mostly because it was already sagging. Bitcoin opened Friday at $63,418, flat to Thursday, then slid to about $62,750 by mid-morning ET, Yahoo Finance reported. It noted that every trend column from daily to yearly now reads negative. Ether opened at $1,884 and drifted to roughly $1,873.
That keeps the whole month inside the $62,000 to $66,000 band we mapped after Wednesday's in-line CPI print, now testing the floor rather than the ceiling.
Our read cuts two ways. A canceled proposal with a 2027 effective date changes nothing mechanical about this market, and pricing it as a crash catalyst would be an overreaction.
But the bull case for US crypto has leaned heavily on the idea that regulatory clarity was finally, irreversibly arriving. This week that thesis took its first real stress test since the Clarity Act slipped to September. The legislation is in recess, the rulemaking is unscheduled, and the clearest signal from Washington is that even friendly oversight still runs on a calendar outsiders cannot see.