The EU's 21st sanctions package against Russia, adopted by the Council on July 23, bans transactions with 14 crypto service platforms, HTX among them. It adds four designations around the A7 payments network and its A7A5 stablecoin. It also creates a legal power to ban crypto-asset services from entire third countries, which TRM Labs says is a first.
Who is on the list, and what the ban does
The 14 platforms sit outside the EU. TRM Labs places them across Georgia, Panama, the UAE, the Marshall Islands, Kyrgyzstan and Belarus. Most of the names will be unfamiliar outside the sanctions-evasion beat: BitPapa, Rapira, Exnode, Aifory Pro, ABCeX, WhiteBird and the A7-linked entities in Africa.
Two are better known. EXMO has been a fixture of the Russian-speaking retail market for a decade. HTX, listed in the regulation under its legal name Huobi Global SA, is a top-tier global exchange by volume. The UK had already moved on both in May, according to Chainalysis' review of those designations, so the EU step extends coordinated pressure rather than opening a new front alone.
The ban is narrower than the headlines suggest. Coindoo's reading of the regulation is that this is a transaction ban, not an asset freeze. A freeze immobilizes a listed party's assets, while a transaction ban only prohibits covered dealings with it. EU companies and individuals are prohibited from covered dealings with the named entities from their effective dates. It is not a general ban on crypto trading, on every non-EU exchange, or on every platform operating from those six jurisdictions.
The practical question for an EU resident with a balance on a listed platform is when that entity's ban takes effect.
HTX, EXMO, BitPapa, Rapira and ten more.
Four new listings tied to the A7 web, Africa links included.
First framework to cut off a whole jurisdiction.
Largest single batch in four years, per TRM Labs.
Why Brussels built a country-sized tool
The deeper target is the A7 cross-border payments network and the ruble-backed A7A5 stablecoin that runs on it. CoinDesk reports that the system has processed nearly $120 billion and describes it as purpose-built for Russia's sanctions evasion. The package adds four designations tied to that network, including its newer links into Africa. The US and UK went after the same infrastructure earlier.
Our reading is that the new power answers a weakness of designating entities one at a time, because operators can re-register somewhere more accommodating and carry on. Instead of chasing entities across Georgia, Kyrgyzstan or Panama, the EU can ban crypto-asset services from a whole jurisdiction if it decides that country hosts evasion infrastructure.
TRM Labs says the aim is deterrence. The message goes to the host country's regulators, not only to platform operators. Whether Brussels ever uses the power is a separate question. A country-wide ban would also hit legitimate businesses, and that cost is what gives the threat weight.
Two things can be checked from here. One is the effective date for each listed entity, since the ban applies from those dates. The other is whether the EU ever names a country under the new power, which would be the first use of it.
How the market took it
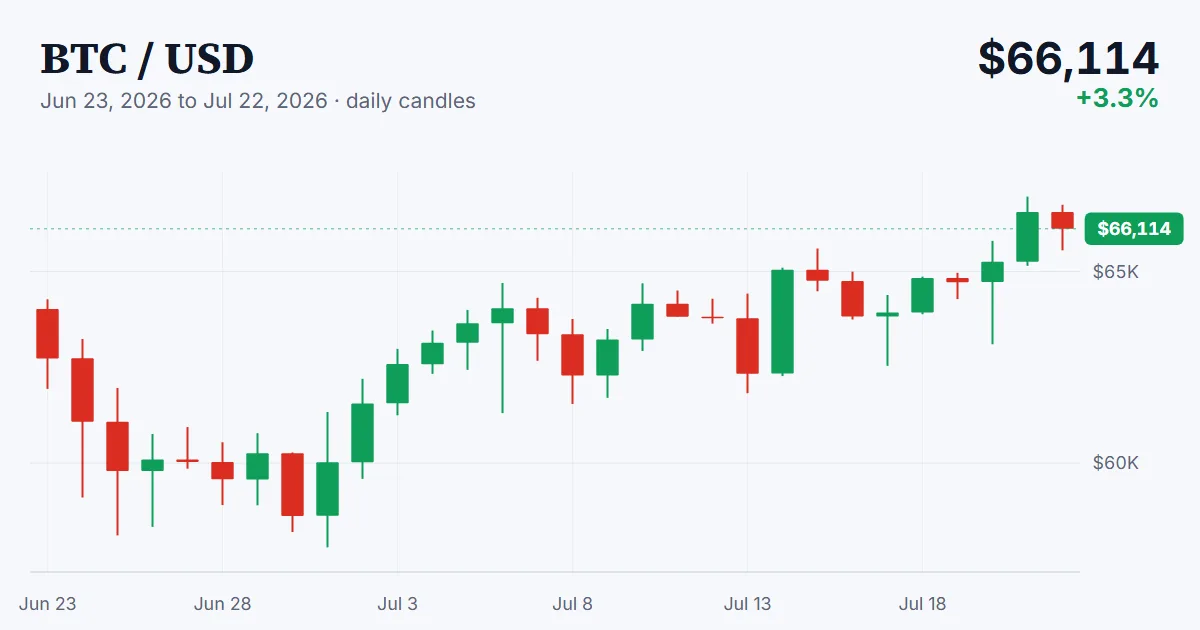
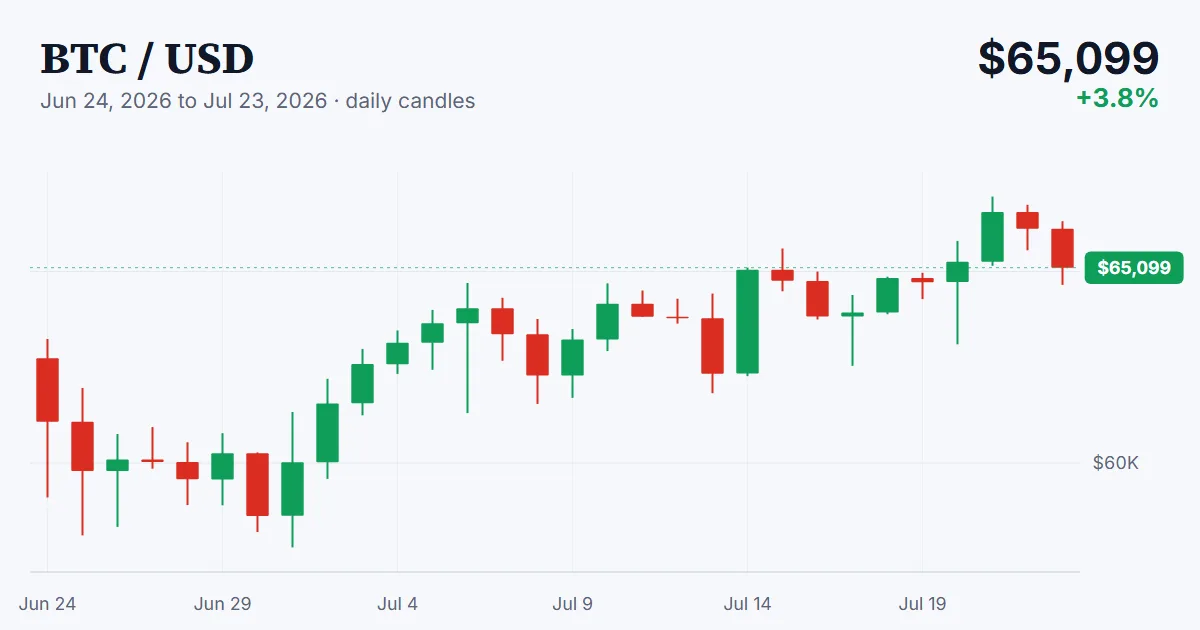
Prices barely moved. Coingabbar's July 25 update has bitcoin down 1.3 percent at about $64,034 and ether near $1,857. Total market capitalization sat near $2.28 trillion, with the Fear and Greed index at 27, still fearful but well off last month's reading of 12.
In our view the calm makes sense. The measures target laundering rails that mainstream crypto users rarely touch, and the week's main price catalyst remains the Fed meeting on July 28 and 29, the same setup as when bitcoin stalled into Fed week.
The regulatory picture split in the same 48 hours. Argentina drafted a bill to pull bitcoin into regulated funds, while industry groups pressed the US Senate on the Clarity Act. Governments are no longer deciding whether to regulate crypto. They are choosing which parts to bring inside the regulated system, and building sharper tools for the rest.