T. Rowe Price launched the T. Rowe Price Active Crypto ETF, ticker TKNZ, on NYSE Arca on July 16. The $1.9 trillion Baltimore asset manager calls it the industry's first actively managed multi-token spot exchange-traded product, according to its press release. The fund debuted with about $15 million in assets and a 0.75 percent net management fee.
The fee is contractually capped until May 2027, after which it rises to 0.90 percent. Instead of tracking a fixed crypto index, the fund's managers adjust holdings on judgment. They can overweight tokens they like and trim the ones they do not, the way active equity managers have treated stocks for a century.
Existing multi-asset crypto funds on US exchanges track a rules-based basket and rebalance mechanically. TKNZ's managers can overweight, trim or exit tokens at will. That flexibility is why the fee is 0.75 percent while passive single-asset funds charge as little as 0.25 percent. Whether the judgment earns the gap is the open question.
T. Rowe Price is one of the few large houses that never stopped arguing that active management earns its fee, so the move into crypto fits the firm. The risk is that in this asset class one index decision, how much Bitcoin versus everything else, dominates returns. The fund now tests that thesis in public.
What the managers picked first
Bitcoin anchors the fund at 40.75 percent, a clear underweight against Bitcoin's dominant share of total crypto market capitalization. Ether takes 18.42 percent. The reported launch allocation then runs through BNB at 11.01 percent, Solana at 9.44 percent and XRP at 9.37 percent.
Hyperliquid's HYPE follows at 6.45 percent, then Stellar's XLM at 3.00 percent and Dogecoin at 1.28 percent. A 0.16 percent USDC sleeve holds the cash.
- BTC 40.75% 40.75%
- ETH 18.42% 18.42%
- BNB 11.01% 11.01%
- SOL 9.44% 9.44%
- XRP 9.37% 9.37%
- HYPE 6.45% 6.45%
- XLM + DOGE + USDC 4.44% 4.44%
The HYPE position stands out. Hyperliquid's token enters a mainstream US ETF ahead of Stellar and Dogecoin, an institutional signal that did not exist for the asset a year ago. It lands while the market still speculates about a second Hyperliquid distribution. In our reading, an active manager choosing the token says more than a passive inclusion would, because no index rule forced it in.
The timing test starts immediately
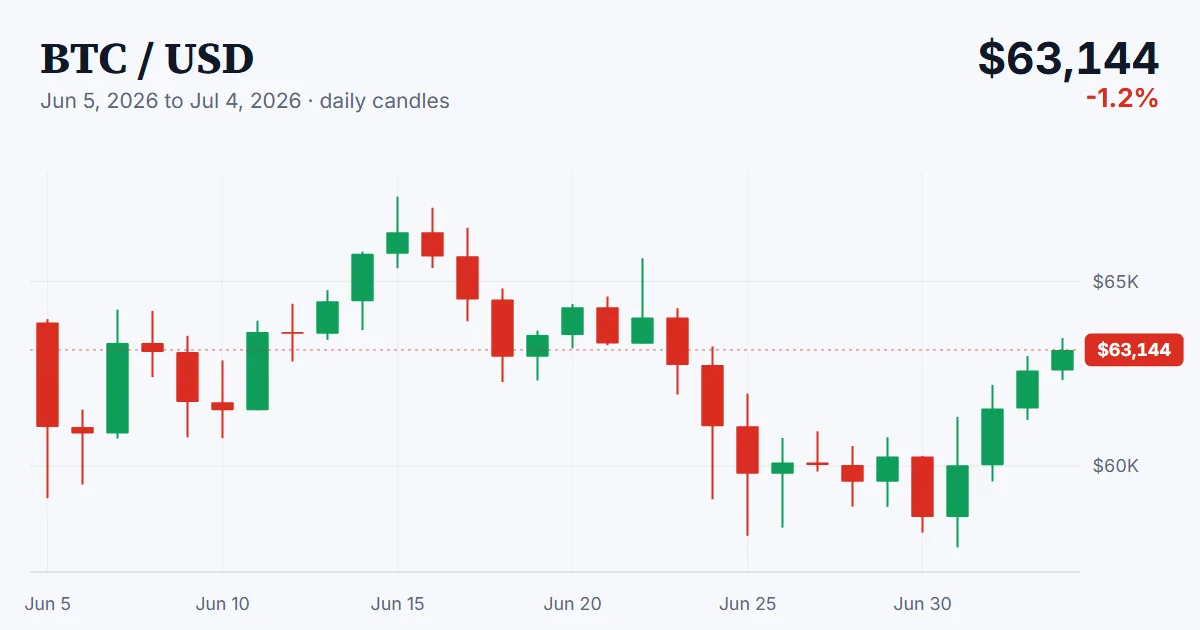
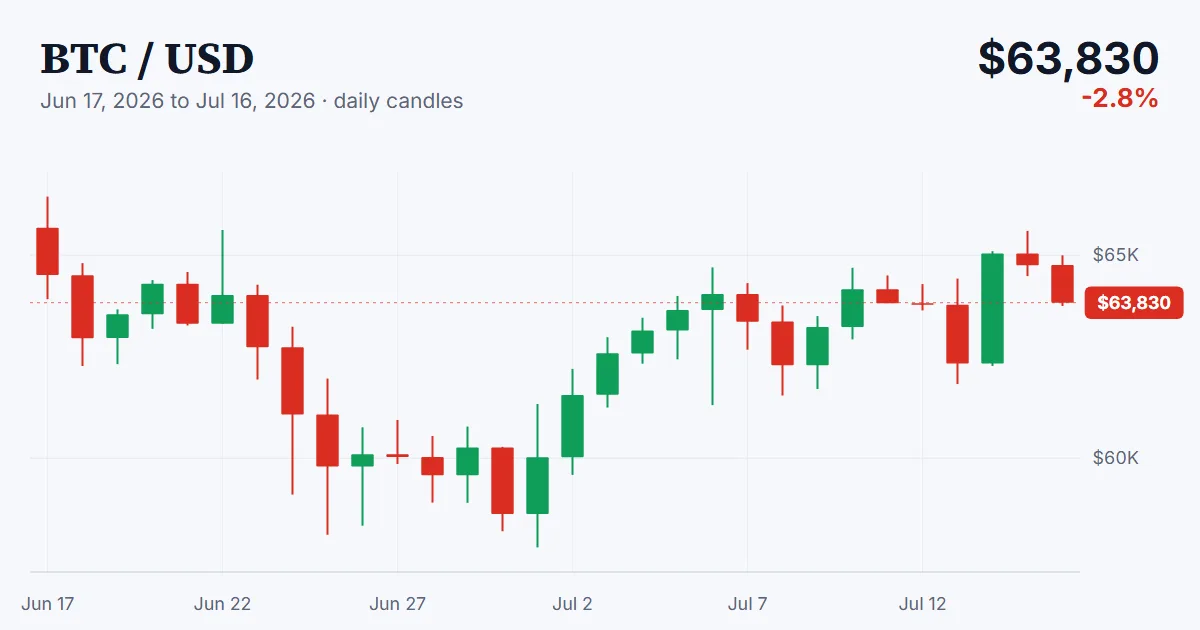
The ETF market TKNZ joins is wobbling. The bitcoin funds shed $424 million on July 13 before recovering $181 million the next day. The ether inflows in our July 16 piece on the ether rotation are running almost entirely through BlackRock's low-fee products.
Launching an actively managed crypto fund into this exact week is either brave or well timed, and the managers get no grace period to find out which. Fee-sensitive passive money picking the cheapest wrapper is the setting in which a 0.75 percent active product has to justify itself trade by trade.
This launch matters less for its $15 million than for what it tests. Suppose TKNZ attracts assets and its judgment calls, the Bitcoin underweight, the HYPE position and the near-zero cash sleeve, beat the passive baskets over a few quarters. Every large manager with an active heritage then has a template to copy.
Suppose instead it trails a plain Bitcoin fund. The industry would learn that crypto's index problem is already solved and that the fee war is what mattered, a dynamic we walked through when the ETF flows first turned this month. Because the managers can change the weights at will, any move away from the debut allocation will show how they use that freedom.