In January, crypto threads called 2026 an airdrop season and attached a five billion dollar figure to it. By July the season's marquee event, OpenSea's SEA, had slid past its March date with no new one. MetaMask and Polymarket had gone from rumor to confirmed and then gone quiet on dates and details. The season is real. The sizing was not.
What happened in six months
The confirmations were genuine progress. OpenSea committed to a community-majority token and then postponed it indefinitely. Consensys put the MetaMask token on the record and shipped a points program instead of a date. Polymarket's executive said there would be an airdrop, and nothing has followed.
The drops that did complete paid little. Monad's November launch is the teaching example: its median allocations valued years of farming at fast-food rates, as the math of ever more farmers sharing each pool predicted.
March 30 launch postponed on market conditions. No new date.
Token on the record; a points program shipped instead of a calendar.
There will be an airdrop, said on the record. Nothing published since.
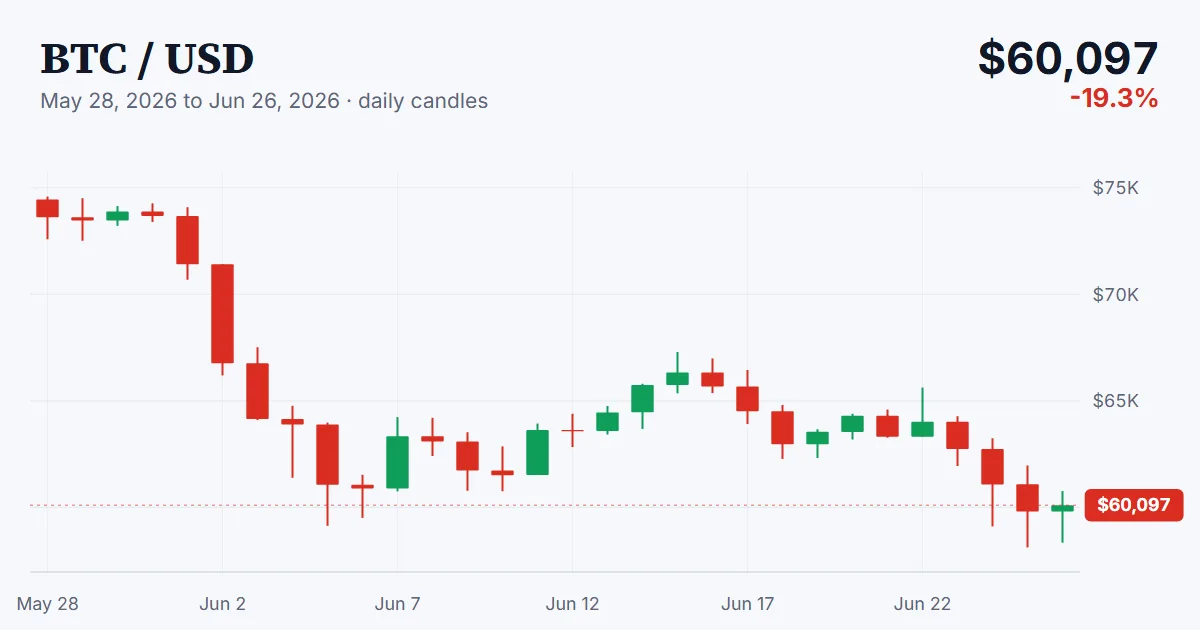
Behind all of it sits the market. With Bitcoin printing two-year lows in June and risk capital defecting to AI equities, every team holding an unlaunched token has the same incentive: wait. A token debuts once, and few teams want to debut into this market if they can help it. Each project that is confirmed but dateless is, in effect, waiting for the market to reopen.
The wait is not idle for the teams. In our reading, extra months mean more snapshot history to train sybil filters on, the checks that screen out one person running many wallets. They also mean longer points seasons to separate committed users from casual ones, and healthy-looking engagement charts for the eventual exchange pitch. Criteria tend to harden while calendars slip. The wallets that survive are those whose activity would look reasonable even if no token existed, which is also the cheapest activity to maintain.
The structural shift under the cycle
Strip out the bear market and something more permanent is visible: the industry converged on points programs as the standard pre-token design. A points program awards points for activity and converts them into an allocation later, on terms the project sets. Retroactive drops, which rewarded past usage that came with no promise of a reward, favored discovery: being early to something good before it was obvious.
Points reward endurance instead, months of legible activity against partly published rules, and they give teams room to tune allocations down without ever technically breaking a promise. A 2026 farmer is closer to an unpaid loyalty-program member holding an option.
Selection discipline, in practice, comes down to three rules.
- Cap concurrent farms at a handful, because attention is this season's scarce asset, not capital.
- Weight confirmed commitments over expected ones, and expected over speculative, roughly in that order of hours spent.
- Re-run the value math the day a program publishes terms, and be willing to walk away from months of points if the arithmetic is poor.
Our advice through the shift has not changed, and the half-year supports it. Concentrate on credible, evidence-backed drops, the kind of board the tracker curates. Farm with activity you would do anyway, so the option costs nothing. Run the value-per-point arithmetic the day tokenomics publish, and be prepared for small numbers.
Casual farmers leaving does not mean the season is dying. It is repricing to a realistic hourly rate, and selective, patient farmers are the only participants that rate still pays.
Three things can be checked in the second half of the year: a launch date from OpenSea, a date from MetaMask, and published criteria from Polymarket. Until each appears, the board stays at confirmed but dateless.